Why You May Keep Getting Rejected for a Pre-approved Mortgage
Getting pre-approved for a mortgage is a first step towards buying a house. Suppose your pre-approval is rejected? Though disappointing, it doesn’t mean your home-buying dreams are forever ended. Why was it rejected and how can you improve prospects of getting approval in future.
What Is Mortgage Pre-approval?
Source: Pexels
A mortgage pre-approval is a letter from a lender that states you’ll likely qualify for a mortgage loan based on the financial details provided. The letter includes how much money you may be approved for. The pre-approval process varies for every lender. Some request only basic details like your name, annual income, and estimated credit score, while others need credit checks and full documentation of finances. A pre-approval is neither a mortgage approval, nor a funding guarantee. Pre-approvals assist the home-buying process, laying a prospective budget, and reassure sellers that you can secure financing.
Why Do Lenders Deny Preapprovals?
Lenders deny applicants for various reasons, but much depends on perceived risks. As per Consumer Financial Protection Bureau’s (CFPB) analysis of 2019 mortgage-application denials, high debt-to-income (DTI) ratios led to 33% of denied mortgage applications while poor credit history was the next common reason for denials. 8.9% of mortgage applicants in 2019 were turned down. The Home Mortgage Disclosure Act requires lenders to report why mortgage applications were rejected, but the same reporting standards do not apply for denied preapprovals.
Your Debt-to-Income Ratio Is High Or Your Credit History Is Poor
Source: Pexels
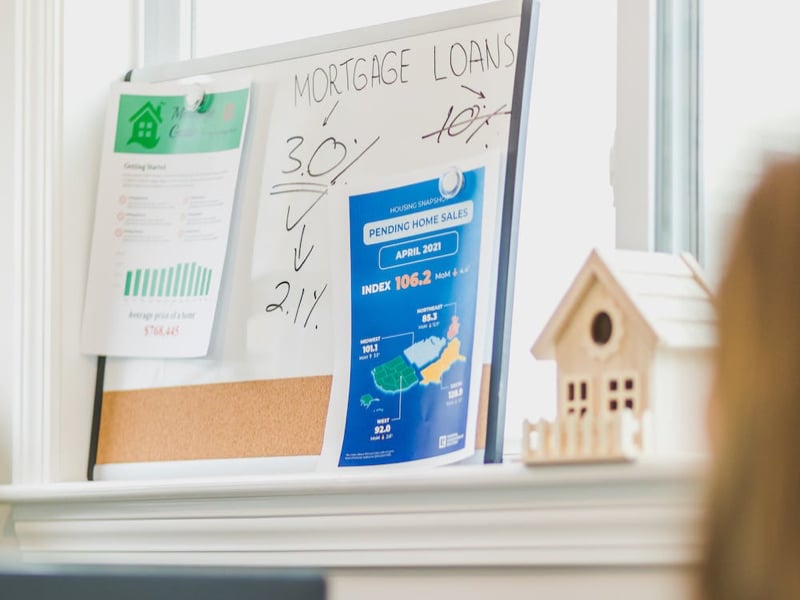
Your DTI reflects how much of your monthly income services your debts, including things like credit card bills, student loan repayments, and expected future mortgage payments. Of the applications denied, around 30% were due to DTI, as per CFPB analysis. Most lenders prefer a DTI lower than 43%. Your credit history plays a role as lenders review your payment habits, how much credit limit you used and the various credit cards and loans secured. Late payments, accounts in collection, and very high debts could factor a denial. About 19% of denied applications in 2019 were due to poor credit history, as per CFPB. Mortgage lenders tightened lending standards after the coronavirus pandemic by enhancing credit scores and down payment requirements, while some lowered DTI ratio requirements. These ensure more difficult pre-approvals now.
What to Do If You’re Denied
Source: Pexels
If your lender rejects your application for preapproval, ascertain reasons to identify the issues involved and prepare an action plan to resolve issues:
Improve credit scores: Pay off balances on your credit cards, settle accounts in collections, reduce overdue payments, and inform credit bureaus of errors in the credit report.
Be consistent: Pay all bills on time and ensure steady employment. These boost approval chances.
Repay your debts: Reduce debts to lower DTI ratio under 43%.
Locate additional income sources: Increasing income reduces DTI. Take on a side gig or ask for a raise; lenders typically take past two years of income into account when assessing ability to repay mortgage. Applying to several lenders helps as qualifying requirements vary by lender.
The Bottom Line
Having your pre-approval application denied, doesn’t mean your home-buying idea is shot. Ascertain reasons for denial to remedy issues involved, by reviewing your credit report often and evaluating improvements. Seek the services of a credit/ housing counselor to prepare the best strategy for credit access.
More in Investments & Savings
-
`
 Russian Billionaires Wealth Surge Despite Sanctions, New Analysis Shows
Sanctions were meant to squeeze Russia’s elite, but the latest numbers tell a different story. According to Forbes Russia, the total...
May 10, 2026 -
`
 Americans Plan to Save Their 2026 Tax Refunds, but Most Will Stash the Cash in Low-Interest Accounts: Report
Americans are walking into the 2026 tax season with a clear goal. They want to save more money, and they see...
May 1, 2026 -
`
 “Time is the Real Flex,” and ‘Luxury Wellness’ Means Slowing Down on Purpose, Says Jonathan Boynton
The idea of luxury has changed, and Jonathan Boynton-Lee is calling it out in plain terms. In a recent interview with...
April 25, 2026 -
`
 The Decline of Startup Funding. What’s Driving It?
The Regulation Crowdfunding market just hit a rough patch, and the numbers tell a clear story. In Q1 2026, total capital...
April 19, 2026 -
`
 Wealthy Elites are Going Big to Help “De-extinct” Wildlife
For most of the 20th century, conservation followed a familiar path. Governments led the charge, backed by treaties and public funding....
April 12, 2026 -
`
 Having No Savings Is Actually More Dangerous Than Carrying Debt, Here’s Why
Most people assume debt is the worst financial position to be in. That belief feels logical because debt comes with interest,...
April 5, 2026 -
`
 5 Practical Ways to Verify GoFundMe Legitimacy
Online fundraisers help people during medical emergencies, disasters, and personal crises. Millions of donors give money every year through GoFundMe because...
March 25, 2026 -
`
 Indian Tycoon Nirmal Jain Places His Biggest Bet on the Country’s Wealth Management Boom
India’s wealth market is heating up, and billionaire investor Nirmal Jain wants a bigger share of it. The founder of IIFL...
March 19, 2026 -
`
 Alphabet Secures $20 Billion in Debt With Rare 100-Year Bond to Fund AI Infrastructure
Alphabet just made a bold financial move that caught the attention of Wall Street and the tech industry. Google’s parent company...
March 11, 2026
More From Refinance Gold
-
 Can ‘Average’ Millennials Retire As Millionaires?
A million-dollar retirement account can sound wildly ambitious when your current 401(k) balance has only five digits. For many millennials, though,...
Top Bank AccountsSeptember 26, 2026 -
 Why the New Generation of Renters Is Ditching Homeownership and Investing in the Stock Market
For generations, buying a home marked a major step toward financial security in America. Younger Americans are starting to question that...
Investments & SavingsSeptember 19, 2026 -
 This Rare, Two-Home Oceanfront Estate in Maui Hits the Market for $45 Million
Finding a private oceanfront home on Maui already takes serious money and patience. Finding two neighboring homes that form one sprawling...
Luxury & Life StyleSeptember 12, 2026 -
 Why Genki’s Crowdfunded Genki Manta Is Its “Most Ambitious Product” Ever
Genki is taking a much bigger swing at gaming hardware with the Genki Manta, a feature-packed pro controller now seeking funding...
Crowd FundingSeptember 4, 2026 -
 How ‘Revenge Saving’ Is Replacing Revenge Spending Among Americans
For a while, spending felt like a reward. After pandemic restrictions eased, Americans booked trips, upgraded wardrobes, ate out more often,...
Top Bank AccountsAugust 27, 2026
You must be logged in to post a comment Login