Never Pull From Your Retirement Accounts When Repaying Debt
As people generally remained at home and spent less money during the pandemic, American credit card debt declined. But as the world revived again, revolving debt increased between October 2021 and March 2022. Credit card spending increased with a volatile stock market and record inflation levels over the past year. Many are examining available options to reduce credit card debts. Financial experts confirm that pulling funds from retirement accounts to repay credit card debt, is a poor option and other alternatives should be considered.
Downsides to Reducing Your Retirement Accounts
Source: Pexels
Due to very high interest on credit cards, your debt balance isn’t reducing appreciably by making minimum payment. While lump sum payments are more effective, you need funds that many people rarely have on hand and consumers may turn to money in their retirement accounts. Financial experts agree that it’s unwise to tap your retirement account to repay debt, even for high-interest debt like credit cards, due to a nasty tax bill and a penalty on top of taxes, which lands you in a tougher situation if you lack the liquidity to pay off debt. In a pre-tax retirement account like a traditional IRA or 401(k) plan, you pay income tax for any money withdrawn. Depending on annual income, tax rate ranges up to 37%, and is excessively steep, with an additional 10% penalty for early withdrawals. Thus, a significant portion of withdrawn funds ends up going to the IRS. This has a significant impact later when you are not working, and rely on those funds. Your retirement portfolio stops growing and compounding if you withdraw the money from retirement accounts. You may even have a shortfall during retirement.
Source: Pexels
Withdrawing $10,000 from a retirement account may eliminate credit card debt but retaining that money in your retirement account and without adding a single dollar, at a conservative estimate of 8% annual return, it exceeds $100,000 after 30 years, due to compound interest. Not touching investments, makes sense.
The Rules on 401(k) Withdrawals
Credit card debt may be unmanageable, but more options are possible. A debt snowball or debt avalanche calculator to examine how quickly debt could be repaid by allocating some excess disposable income every month. Repaying debt with money from your 401(k) plan makes sense in some cases, but reducing retirement savings is avoidable by considering preferable alternatives as under: If you use money from your 401(k) plan before you turn 59.5, you will generally have to pay a 10% penalty in income tax, because of premature withdrawal. After age 59.5, you will only have to pay tax on traditional 401(k) and IRAs (withdrawals for the Roth versions are tax-free). There are alternatives to 401(k) withdrawals for paying back debt, including 401(k) loans. The rules that apply on withdrawing money from your 401(k) plan depends on your age, the kind of 401(k) you have, and what your particular plan allows, after five years.
Source: Pexels
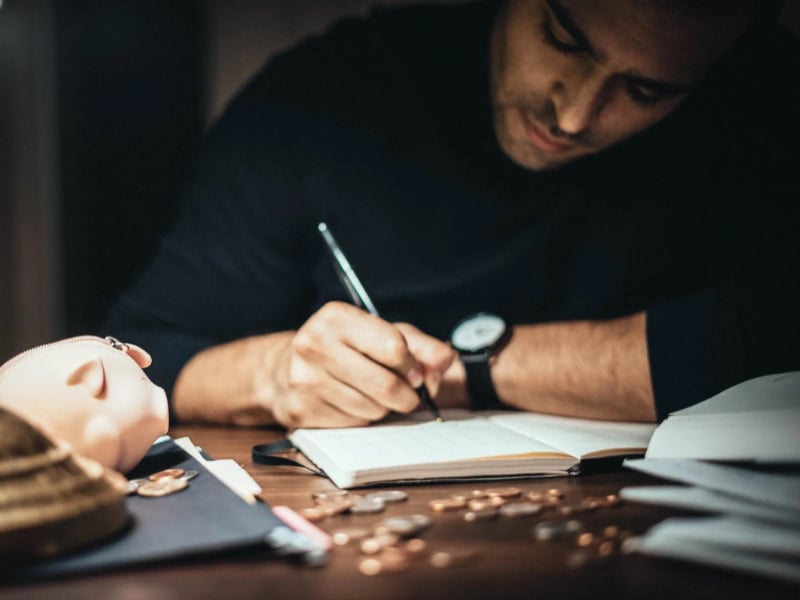
If you withdraw $45,000 from your 401(k) to pay off debt, a 10% ($4,500) early withdrawal penalty is imposed and you pay income tax on the $45,000. But if you’re single, and taxable income is $100,000, your $45,000 withdrawal is taxed at 24%, or $10,800. Thus your $45,000 withdrawal costs you $15,300 and leaves only $29,700 to reduce your debts.
More in Investments & Savings
-
`
 Americans Plan to Save Their 2026 Tax Refunds, but Most Will Stash the Cash in Low-Interest Accounts: Report
Americans are walking into the 2026 tax season with a clear goal. They want to save more money, and they see...
May 1, 2026 -
`
 “Time is the Real Flex,” and ‘Luxury Wellness’ Means Slowing Down on Purpose, Says Jonathan Boynton
The idea of luxury has changed, and Jonathan Boynton-Lee is calling it out in plain terms. In a recent interview with...
April 25, 2026 -
`
 The Decline of Startup Funding. What’s Driving It?
The Regulation Crowdfunding market just hit a rough patch, and the numbers tell a clear story. In Q1 2026, total capital...
April 19, 2026 -
`
 Wealthy Elites are Going Big to Help “De-extinct” Wildlife
For most of the 20th century, conservation followed a familiar path. Governments led the charge, backed by treaties and public funding....
April 12, 2026 -
`
 Having No Savings Is Actually More Dangerous Than Carrying Debt, Here’s Why
Most people assume debt is the worst financial position to be in. That belief feels logical because debt comes with interest,...
April 5, 2026 -
`
 5 Practical Ways to Verify GoFundMe Legitimacy
Online fundraisers help people during medical emergencies, disasters, and personal crises. Millions of donors give money every year through GoFundMe because...
March 25, 2026 -
`
 Indian Tycoon Nirmal Jain Places His Biggest Bet on the Country’s Wealth Management Boom
India’s wealth market is heating up, and billionaire investor Nirmal Jain wants a bigger share of it. The founder of IIFL...
March 19, 2026 -
`
 Alphabet Secures $20 Billion in Debt With Rare 100-Year Bond to Fund AI Infrastructure
Alphabet just made a bold financial move that caught the attention of Wall Street and the tech industry. Google’s parent company...
March 11, 2026 -
`
 London Designers Embrace Everyday Luxury and Lifestyle
Design coming out of London has started to feel more grounded lately. Rather than chasing dreamy concepts, many creatives are focusing...
March 6, 2026
More From Refinance Gold
-
 Why the New Generation of Renters Is Ditching Homeownership and Investing in the Stock Market
For generations, buying a home marked a major step toward financial security in America. Younger Americans are starting to question that...
Investments & SavingsSeptember 19, 2026 -
 This Rare, Two-Home Oceanfront Estate in Maui Hits the Market for $45 Million
Finding a private oceanfront home on Maui already takes serious money and patience. Finding two neighboring homes that form one sprawling...
Luxury & Life StyleSeptember 12, 2026 -
 Why Genki’s Crowdfunded Genki Manta Is Its “Most Ambitious Product” Ever
Genki is taking a much bigger swing at gaming hardware with the Genki Manta, a feature-packed pro controller now seeking funding...
Crowd FundingSeptember 4, 2026 -
 How ‘Revenge Saving’ Is Replacing Revenge Spending Among Americans
For a while, spending felt like a reward. After pandemic restrictions eased, Americans booked trips, upgraded wardrobes, ate out more often,...
Top Bank AccountsAugust 27, 2026 -
 38-YO Investor Lost $60,000 in the Stock Market Wipeout and Is Now Turning to Real Estate for Safety
Watching an investment portfolio fall is uncomfortable. But watching $60,000 disappear within weeks can change how someone thinks about risk altogether....
Investments & SavingsAugust 21, 2026
You must be logged in to post a comment Login